Article 1: The Core Philosophy – Why the 50/30/20 Framework Works
Most personal budgeting systems fail because they require unrealistic micromanagement. Tracking every cup of coffee, logging grocery receipts, and categorizing dozens of micro-transactions creates cognitive fatigue. Within weeks, most people abandon their spreadsheets and return to reactive spending.
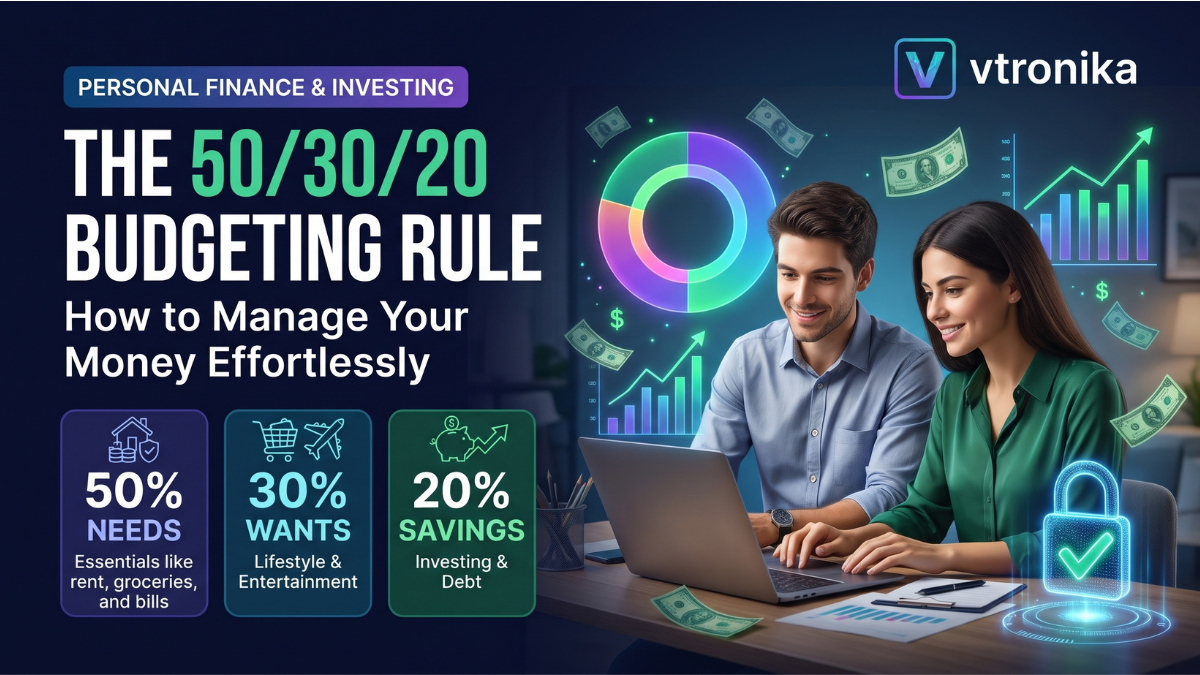
The 50/30/20 Rule—originally popularized by bankruptcy expert and Harvard law professor Elizabeth Warren—solves this problem by shifting from micro-tracking to macro-allocation. It divides your after-tax (take-home) income into three simple buckets:
- 50% for Needs: Absolute survival essentials and contractual obligations.
- 30% for Wants: Lifestyle choices, entertainment, and personal comfort.
- 20% for Savings and Debt Payoff: Wealth generation, emergency reserves, and long-term security.
Instead of obsessing over individual line items, your sole job is keeping total expenditures within these three high-level guardrails. This macro approach provides immediate structural clarity, prevents lifestyle creep, and builds wealth automatically without sacrificing day-to-day peace of mind.
Article 2: Calculating Net Income – The Starting Baseline
The most critical mathematical mistake when setting up the 50/30/20 system is calculating percentages against gross earnings rather than net take-home pay. Percentages based on gross income will distort your numbers, because taxes, social security, and mandatory payroll deductions are money you never actually receive in your bank account.
To establish your baseline:
- Salaried Employees: Examine your paystub. Your net baseline is your direct deposit figure plus any voluntary retirement contributions already deducted at source (such as 401(k) or provident funds). If retirement deductions were already taken out pre-tax, add them back to your net income to assess your true savings rate accurately.
- Freelancers and Variable Earners: Calculate your average monthly revenue over the trailing 6 to 12 months. Subtract business expenses and reserve 25% to 30% for estimated taxes in a separate account. The remaining figure is your true personal take-home pay.
Once you know this exact net dollar figure, multiply it by 0.50, 0.30, and 0.20 to set your non-negotiable monthly ceilings and floors.
Article 3: Deconstructing the 50% “Needs” Bucket
The “Needs” category represents baseline survival costs. An easy way to test whether an expense is a genuine need is to ask: “If I lost all income tomorrow, would cutting this immediately threaten my shelter, physical health, or basic livelihood?”
True essentials include:
- Shelter: Rent, mortgage payments, property taxes, and homeowners/renters insurance.
- Utilities: Electricity, heating, water, and basic home internet (necessary for employment).
- Nutrition: Whole-food groceries and staple cooking supplies (excluding restaurant delivery and dining out).
- Transportation: Basic vehicle payments, gas, auto insurance, or public transit passes required for commuting.
- Healthcare & Minimum Debts: Prescriptions, baseline health insurance premiums, and statutory minimum payments on loans or credit cards (to prevent legal default).
If total essentials exceed 50% of your take-home pay, your budget is structurally vulnerable. In high-cost-of-living areas, this requires deliberate interventions: taking on housemates, refinancing high-interest car loans, or switching to low-cost grocery planning.
Article 4: The 30% “Wants” Bucket – Guilt-Free Lifestyle Spending
Traditional budgeting often treats entertainment and leisure as moral failings, preaching total deprivation. This approach is psychologically unsustainable; extreme frugality usually leads to burnout followed by aggressive binge spending.
The 50/30/20 rule addresses human nature by deliberately allocating 30% of net income to discretionary spending. This money is designed to be spent without guilt:
- Socializing: Dinners out with friends, drinks, and celebration events.
- Media & Digital Services: Streaming subscriptions (Netflix, Spotify), gaming, and premium software.
- Comfort & Hobbies: Gym memberships, athletic gear, weekend travel, and festival tickets.
- Aesthetic Upgrades: Designer apparel, salon services beyond basic grooming, and home decor.
The key rule is hard-capping this bucket at 30%. When the money is gone for the month, discretionary spending pauses until the next pay cycle begins.
Article 5: Needs vs. Wants – Resolving the Grey Zones
The fastest way the 50/30/20 system gets compromised is through “need creep”—rationalizing discretionary desires as survival essentials. Misclassifying wants as needs artificially shrinks the savings bucket.
[Basic Need]                   ---> [Creep into Want]
Staple groceries for cooking        UberEats delivery & gourmet pre-made meals
Reliable commuter sedan            $750/month luxury SUV lease
Basic functional smartphone        Annual flagship upgrade on installment
Work wardrobe essentials            High-end designer label shopping
To resolve these grey zones, practice unbundling:
- The baseline cost of groceries is a Need; high-end organic snacks and alcohol are Wants.
- A reliable mobile phone and basic data plan is a Need; unlimited 5G with top-tier device financing is a Want.
- Your minimum loan payment is a Need; extra payments toward early principal payoff belong in the Savings/Debt (20%) bucket.
Separating essential functionality from comfort upgrades ensures your core budget numbers remain accurate.
Article 6: The 20% “Wealth” Engine – Savings and Debt Payoff
The 20% category is the engine that builds long-term financial independence. It does not sit idly in a low-interest checking account; it is put to work building safety nets and compounding capital.
The optimal chronological order for the 20% bucket:
- The Starter Emergency Buffer: Build a liquid cash reserve of 1 to 2 months of basic expenses in a high-yield savings account to prevent minor emergencies from turning into credit card debt.
- High-Interest Debt Eradication: Aggressively pay down toxic consumer debts (credit cards, payday loans, high-interest personal loans exceeding 7–8% APR).
- The Full Emergency Runway: Expand your emergency fund to cover 3 to 6 months of true living costs.
- Long-Term Investing: Direct the entire 20% allocation toward diversified index funds, retirement accounts, or low-cost mutual funds to harness the power of compound returns over decades.
Article 7: Adapting the Rule – High Cost of Living (HCOL) Adjustments
In major metropolitan areas, housing costs alone can consume 45% to 55% of an individual’s take-home pay, making a strict 50/30/20 split impractical. Forcing a rigid framework onto an incompatible economic reality leads to frustration and abandonment.
When operating under tight financial constraints, adopt adjusted allocations:
| Financial Scenario | Needs | Wants | Savings & Debt |
| Standard 50/30/20 | 50% | 30% | 20% |
| High Cost of Living (HCOL) | 60% | 20% | 20% |
| Aggressive Debt Payoff | 50% | 15% | 35% |
| Early Retirement (FIRE) | 40% | 10% | 50% |
The non-negotiable rule when adapting the framework: Protect the Savings allocation. If your Needs rise to 60%, the extra 10% must come out of your Wants, not your Savings. Never drop your wealth-building allocation below 10% to 15% unless facing immediate insolvency.
Article 8: Automation Architecture – “Paying Yourself First”
Relying on manual transfers at the end of the month almost guarantees failure. When people save whatever remains after four weeks of spending, there is usually nothing left. High performers implement a “Pay Yourself First” automated cash pipeline.
                  [Employer Payroll Direct Deposit]
                                  |
              +-------------------+-------------------+
              |                                       |
    [Needs Account (50%)]                   [Savings Account (20%)]
  Rent, Bills, Utilities                 Auto-routed immediately on payday
              |                                       |
    [Wants Account (30%)]                [Investments / Debt Payoff]
  Discretionary spending debit card        Index funds & loan amortization
Set up automatic transfers on the day your paycheck arrives:
- 20% routes instantly to high-yield savings or investment brokerage accounts.
- 50% remains in your primary checking account dedicated exclusively to bills and essentials.
- 30% routes to a separate digital checking account or debit card dedicated solely to lifestyle spending.
When discretionary funds run low on your secondary card, you stop spending. The rest of your financial life continues running on autopilot.
Article 9: Taming Lifestyle Inflation as Income Scales
As careers progress and earnings climb, an insidious phenomenon known as lifestyle creep often takes hold. A 20% raise is frequently met with an immediate 25% increase in spending: upgrading to a luxury apartment, leasing a newer vehicle, and dining at pricier restaurants. Consequently, professionals earning six figures can find themselves living paycheck to paycheck just as easily as entry-level workers.
The 50/30/20 rule naturally counters lifestyle creep because it is based on percentages rather than fixed dollar amounts:
- If your monthly net pay is $3,000, you live on $1,500 in needs, spend $900 on lifestyle, and save $600.
- If your net pay increases to $6,000, your lifestyle budget naturally expands to $1,800 (giving you more freedom), while your monthly savings automatically jump to $1,200.
For accelerated wealth generation, apply the 50% Promotion Rule: whenever you receive a raise or bonus, allocate at least 50% of the net increase directly into your savings and investment bucket, letting the remainder absorb minor lifestyle upgrades.
Article 10: Quarterly Auditing – Refining the System Over Time
Budgeting is not a one-time project; it is an evolving management system. While the day-to-day operations run on automated pipelines, financial conditions naturally change throughout the year. Conducting a focused 30-minute quarterly audit keeps your allocations aligned with your real-world goals.
Checklist for your quarterly review:
- Audit Recurring Subscriptions: Review the past 90 days of bank statements. Cancel unutilized streaming accounts, dormant software licenses, and unused gym memberships.
- Re-evaluate Utility and Insurance Rates: Shop home and auto insurance rates once a year, and negotiate internet and phone bills. Reducing baseline needs creates breathing room in your budget.
- Recalibrate Allocation Percentages: If a consumer debt has been cleared or a car loan paid off, reassign those monthly funds directly into long-term investments rather than letting them slip back into lifestyle spending.
- Celebrate Progress: Track your net worth trajectory every quarter. Watching your emergency reserves grow and investment balances climb reinforces the behavioral habits that sustain lifelong financial independence.